

Bonded Warehouse Meaning
In "bonded warehouse", the bond belongs to the operator. The warehouse proprietor holds a custodial bond with US Customs and Border Protection (CBP), a continuous bond in which it agrees to act as custodian of the bonded goods it receives, accept only merchandise CBP regulations authorize, and keep the records CBP requires and produce them on demand (19 CFR 113.63).
The status comes from CBP itself. The owner or lessee of a facility applies in writing to the director of the CBP port nearest the warehouse, describing the premises and the class of warehouse it wants, and executes the custodial bond once the application is approved (19 CFR 19.2). After approval, CBP keeps oversight: officers can review the proprietor's books, count the stock on hand and check individual transactions (19 CFR 19.4).
Two of CBP's classes are general storage warehouses. Class 2 is an importer's private bonded warehouse, holding only its own goods; Class 3 is a public bonded warehouse open to any importer (19 CFR 19.1). The other warehouse classes cover bulk goods, manufacturing and other special uses, and the warehouse types guide shows where public bonded warehouses, private bonded warehouses sit among other facilities. Bonded warehousing is one of the customs tools behind international trade and logistics; this guide covers the US rules.
From Warehouse Entry to US Release or Export
Entry for Warehouse
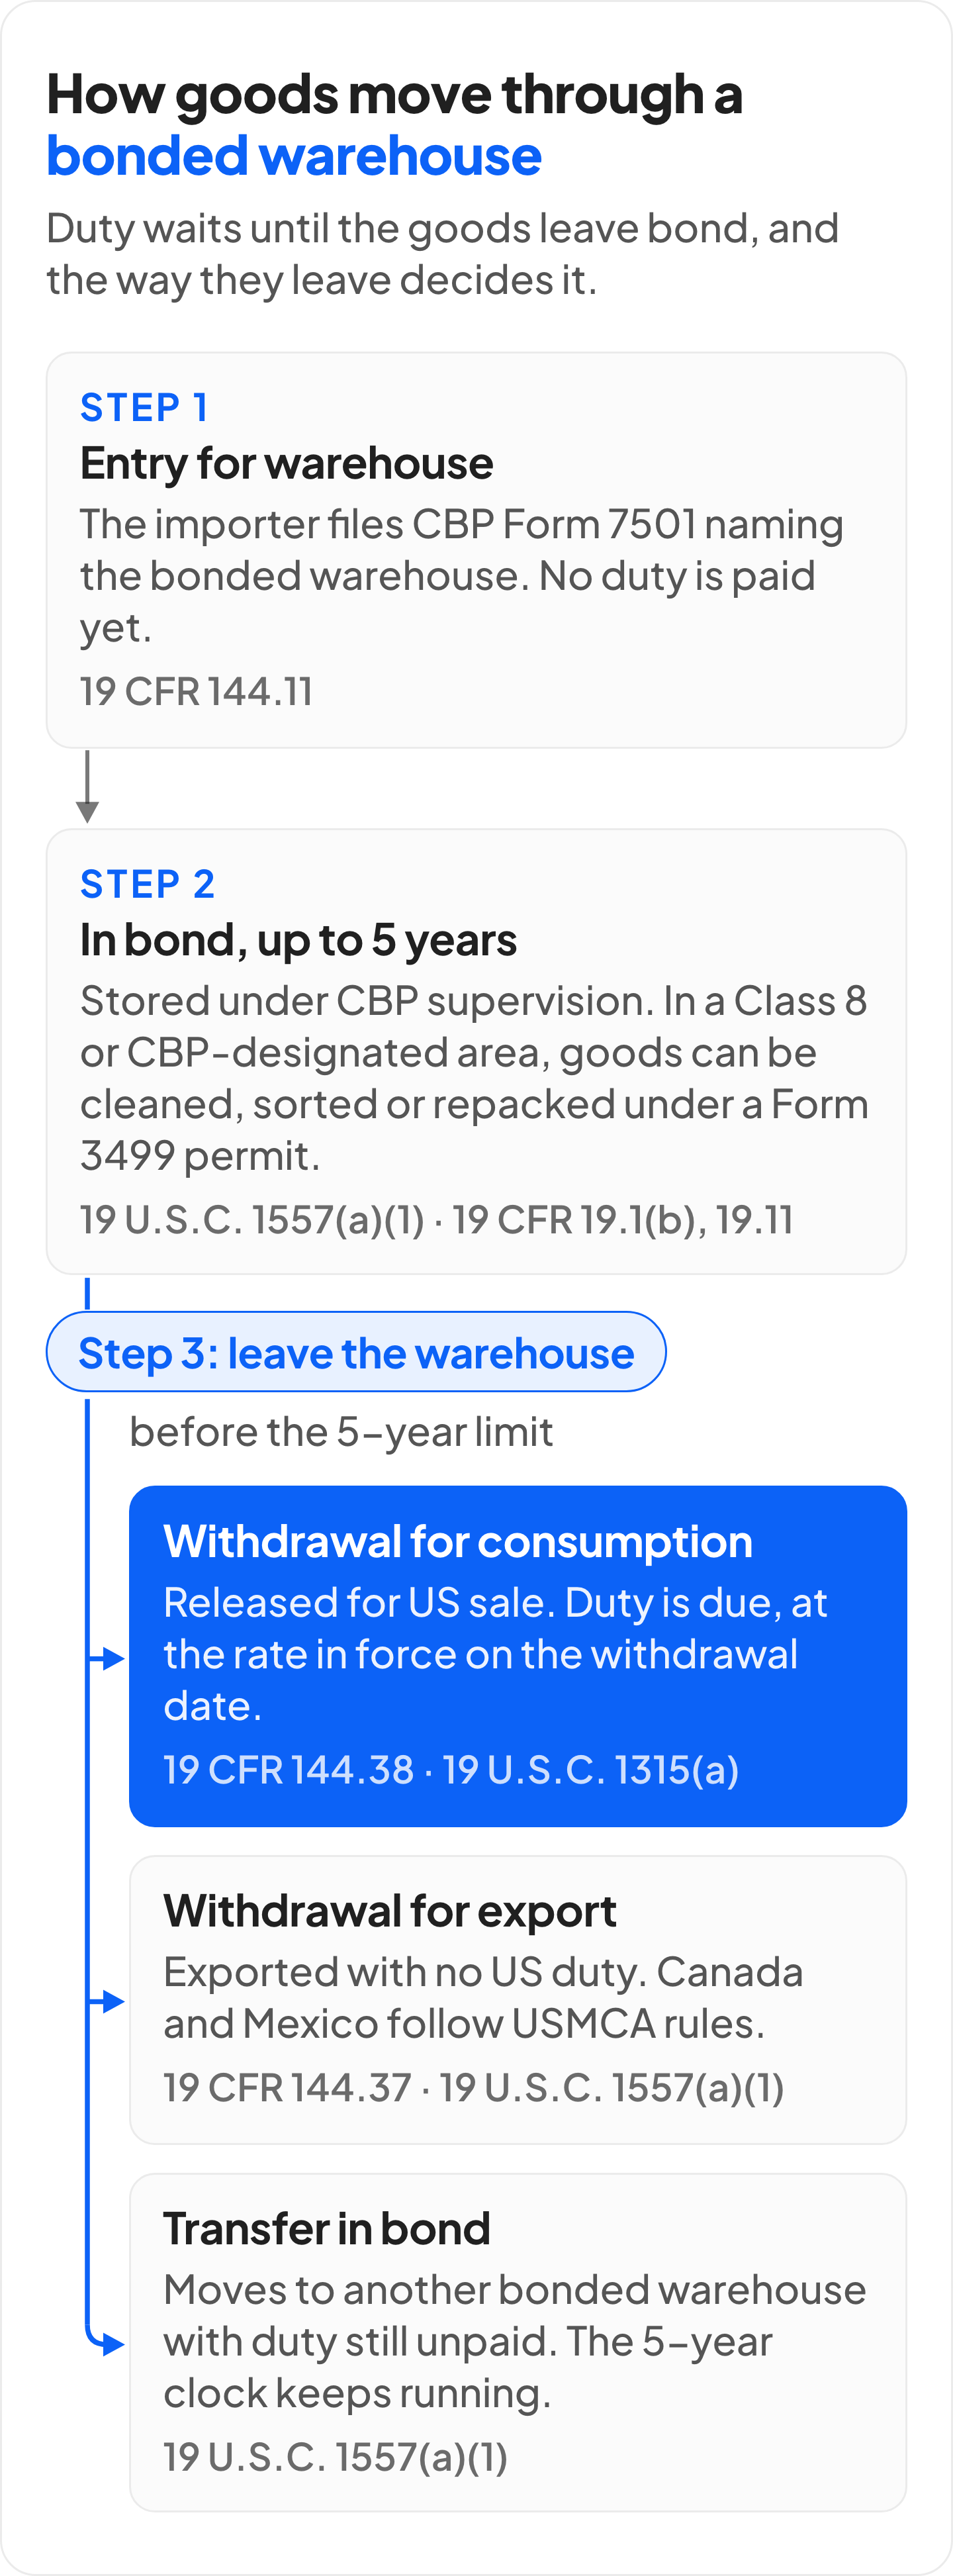
Goods go into bond on a warehouse entry instead of a consumption entry. The importer, often through a customs broker, files CBP Form 7501 (or its electronic equivalent) and names the bonded warehouse where the goods will be stored (19 CFR 144.11). No duty is paid at this stage.
Storage for Up to Five Years
Goods can stay in bond for up to 5 years from the date of importation, not from the date they reach the warehouse. CBP can allow longer only on a request that shows good cause (19 U.S.C. 1557(a)(1)). Goods still in the warehouse with duty unpaid after that are treated as abandoned to the government and sold (19 U.S.C. 1559), so every lot needs a way out before its deadline.
Permitted Manipulation
Goods in bond can be worked on in ways that change their condition without turning them into a new product: cleaning, sorting and repacking are allowed, manufacturing is not (19 CFR 19.1(a)(8)). For a brand, that can mean repacking cartons or sorting out damaged units before any duty is paid on them. Each manipulation needs a prior permit from the port director, applied for on CBP Form 3499, and a blanket permit can cover repeated work for up to a year if the proprietor keeps a running record of quantities before and after (19 CFR 19.11). The work happens in a Class 8 manipulation warehouse, or in a part of another bonded warehouse CBP designates as one (19 CFR 19.1(b)); manufacturing needs a different class, Class 6 (19 CFR 19.1(a)(6)).
Withdrawal for Consumption
To sell goods in the US, the importer withdraws them for consumption on CBP Form 7501 and deposits the estimated duty (19 CFR 144.38). Duty is assessed at the rate in force on the withdrawal date, whatever the rate was when the goods landed (19 U.S.C. 1315(a), 19 U.S.C. 1557(a)(1)), so a tariff change while goods sit in bond applies to them when they come out, whether the rate went up or down. A withdrawal can take part of a lot: each one records the quantity before it, the quantity withdrawn and the quantity left (19 CFR 144.32).
Withdrawal for Export
Goods bound for another country are withdrawn for exportation on an in-bond application and leave without paying US duty (19 CFR 144.37, 19 U.S.C. 1557(a)(1)). If they ship out through another port, they move there in bond with a bonded carrier. Imports that already cleared customs with duty paid take a different route back to that money, duty drawback, which has its own rules.
Exports to Canada or Mexico
Exports to Canada or Mexico follow USMCA rules. A withdrawal for export to either country, or into a duty-deferral program there, counts as a withdrawal for consumption under those rules (19 CFR 144.38(b), 19 CFR 182.53). Goods that leave in the condition they arrived in, even after cleaning, sorting or repacking, still owe no US duty (19 U.S.C. 4534(a)(2)). Goods otherwise changed in bond can owe US duty, reduced by up to the duty paid in Canada or Mexico (19 U.S.C. 1562). Confirm the duty treatment with a customs broker before holding goods in bond for those markets.
What This Means for an Ecommerce Brand
For a brand that imports stock to sell in the US, a bonded warehouse changes when duty is paid, not whether it is paid. Every unit released for US sale leaves on a withdrawal for consumption, and that withdrawal is when its duty falls due. Units exported from bond to buyers abroad owe no US duty, including to Canada or Mexico when they leave in the condition they arrived in.
That makes each withdrawal a replenishment decision. Stock comes in on warehouse entries as it lands, then goes out in portions as the stock the brand sells from runs low, with duty due on each portion as it leaves bond. Each withdrawal is its own CBP filing, so withdrawals timed to the replenishment cycle are easier to run than ad hoc releases.
The de minimis change closed a cross-border shortcut. Duty-free Section 321 entry has been suspended for shipments from all countries since August 29, 2025, so parcels shipped to US buyers from abroad now go through customs entry like any other import. For brands that relied on it, importing in bulk into bonded storage and withdrawing as they sell is one way to pay duty later, and only on what is released for US sale.
Pros and Cons of a Bonded Warehouse
Pros
- Duty deferral (cash flow): Duty is due when goods are withdrawn for consumption, not when they land, so cash is not tied up in duty on stock that has not sold (19 U.S.C. 1557(a)(1)).
- No duty on exports or supervised destruction: Goods exported from bond owe no US duty (to Canada or Mexico, when they leave in the condition they arrived in), and neither do damaged or unsellable goods destroyed under customs supervision at the consignee's request and expense (19 U.S.C. 1557(a)(1) and (c)).
- Preparation before duty: Sorting, cleaning and repacking can happen in bond under a permit, so damaged units are pulled out before duty is paid on them.
Cons
- Product limits: Perishable articles and explosive substances other than firecrackers cannot be entered for warehousing (19 U.S.C. 1557(a)(1)).
- A time limit: 5 years from importation unless CBP extends it for good cause, after which goods with duty unpaid are treated as abandoned.
- Permits for handling: No manipulation without a prior permit from the port director (19 CFR 19.11(c)).
- Records and audits: The proprietor (in a public bonded warehouse, the operator rather than the brand) must run an inventory control and recordkeeping system, keep the records for 5 years after the final withdrawal on each entry, and make them available to CBP (19 CFR 19.4).
- Priced by provider: Bonded storage is a specialist service, and each provider sets its own rates. The bonded warehouse directory lists 3PLs that offer it and covers what drives the cost.
Bonded vs Non-Bonded Warehouse
In a bonded warehouse, imported goods stay under CBP supervision with duty unpaid until they are withdrawn (19 U.S.C. 1557(a)(1)). A non-bonded warehouse sits outside that system: imports reach it only after clearing customs for consumption, so there is no duty deferral, and also no 5-year limit and no manipulation permits. One building can hold both, with the bonded area separated in a way the port director sets, such as a wall, fence or painted line (19 CFR 19.4(b)(6)). A foreign trade zone is the other way to hold imports with duty deferred: see how bonded warehouse time limits compare with a foreign trade zone.