Tariff fraud, usually called customs fraud, is lying to U.S. Customs and Border Protection (CBP) about what an import is, where it was made or what it is worth, so that less duty gets paid. The common schemes are misclassification, undervaluation, false country of origin, transshipment and misuse of the de minimis exemption. It is policed three ways: CBP penalties under 19 U.S.C. 1592, civil False Claims Act suits that carry treble damages, and criminal charges under Title 18.
This guide explains each scheme with a named Justice Department case, what the penalties look like, who investigates, and what it means for importers and the 3PLs that receive, relabel and ship their goods. It covers U.S. law only and is not legal advice.
What Is Customs Fraud?
Every commercial import is entered under a declaration. According to the Justice Department's Resource Guide to Trade Fraud Enforcement (July 2026), CBP calculates the money owed on an entry from three data points: the HTS code, the country of origin and the declared value. A knowing lie in any one of them can cut the customs duty owed, and that is what makes it fraud rather than a paperwork error.
The legal duty sits with the importer of record (IOR), which must use "reasonable care" when it tells CBP what it is bringing in. Most importers file through a licensed customs broker, but the same guide is blunt that the IOR "cannot 'contract away'" its responsibility for the truth of an entry. The broker has its own due diligence duties on top.
The five common customs fraud schemes
Scheme
What is falsified
DOJ example
Misclassification
HTS code or product description
Ford, $365M settlement (2024)
Undervaluation
Declared value, often through a second invoice
Miami truck tire importer, guilty plea (2024)
False country of origin
Origin declaration or origin marking
Ceratizit USA, $54.4M settlement (2025)
Transshipment
Origin, disguised by routing through a third country
Miami truck tire importer, via Canada and Malaysia (guilty plea, 2024)
De minimis misuse
Value or eligibility on low-value parcels
Now moot: the exemption is suspended
The Five Most Common Customs Fraud Schemes
1. Misclassification
Every product has a code in the Harmonized Tariff Schedule, and the code sets the duty rate. Tariff classification fraud means declaring a code with a lower rate than the correct one, for example calling finished goods "parts".
A well-known case involved Ford. In March 2024 Ford agreed to pay $365 million to settle claims that from 2009 to 2013 it presented Transit Connect cargo vans to CBP with sham rear seats so they would be classified as passenger vehicles, paying a 2.5% duty rate instead of the 25% rate for cargo vehicles. DOJ notes that the claims resolved by the settlement are allegations only and that there has been no determination of liability. In May 2026, Perfectus Aluminum and related companies agreed to pay $549.5 million to settle claims that they avoided antidumping and countervailing duties on more than 2.2 million aluminum extrusions by declaring them as finished pallets. According to DOJ, the "pallets" were extrusions spot-welded together, and none were ever sold; a federal jury had convicted the companies of conspiracy in 2021.
2. Undervaluation
Duty is usually a percentage of value, so a lower declared value means a lower bill. The classic method is double invoicing: the supplier issues a real invoice for payment and a lower one for customs. The Justice Department's guide describes exactly this pattern, and notes that false first-sale pricing is another route. Customs valuation rules decide what the declared value must include.
In December 2024, a Miami importer of truck tires pleaded guilty to conspiracy to commit an offense against the United States. According to the Southern District of Florida, in many instances he and his co-conspirators created two sets of invoices, one reflecting the actual value and one that undervalued the tires for CBP, and they caused the Chinese tires to be transshipped through third countries, including Canada and Malaysia. The loss to the United States exceeded $1.9 million.
3. False Country of Origin
Origin decides whether goods face extra duties such as Section 301 tariffs on Chinese products or antidumping duties. A good only changes origin if it is "substantially transformed" in another country; the DOJ guide notes that simple assembly or repacking does not meet that bar. Origin fraud often comes with mismarking, such as replacing the required country of origin label with a sticker from a third country.
In December 2025, Ceratizit USA agreed to pay $54.4 million to resolve allegations that it declared Chinese tungsten carbide products as Taiwanese to avoid Section 301 tariffs, misclassified products under the wrong HTS code, and failed to mark some goods with their origin. The case began as a whistleblower suit, and the whistleblower's share was about $9.75 million. The claims resolved by the settlement are allegations only, and there has been no determination of liability.
4. Transshipment
Transshipment is routing goods through a third country so the paperwork shows that country as the origin. It is the physical side of origin fraud, and DOJ names it first in the Trade Fraud Task Force's mandate, along with mislabeling and false declaration.
Two of the matters above involve it. The Miami tire importer admitted that Chinese tires were transshipped through third countries, including Canada and Malaysia, and the United States alleged that Ceratizit's Chinese-made products were transshipped to Taiwan before being shipped to the U.S.
A false origin claim does not always need a detour. In July 2026, federal prosecutors in Chicago charged the operators of Surya International, a California gold jewelry importer, with falsely declaring Singapore as the origin of jewelry that the charges say was made in India and the United Arab Emirates. The charges allege about 563 entries of jewelry valued at more than $693 million and more than $38 million in avoided duties. These are allegations only; the defendants have not been convicted.
5. De Minimis Misuse
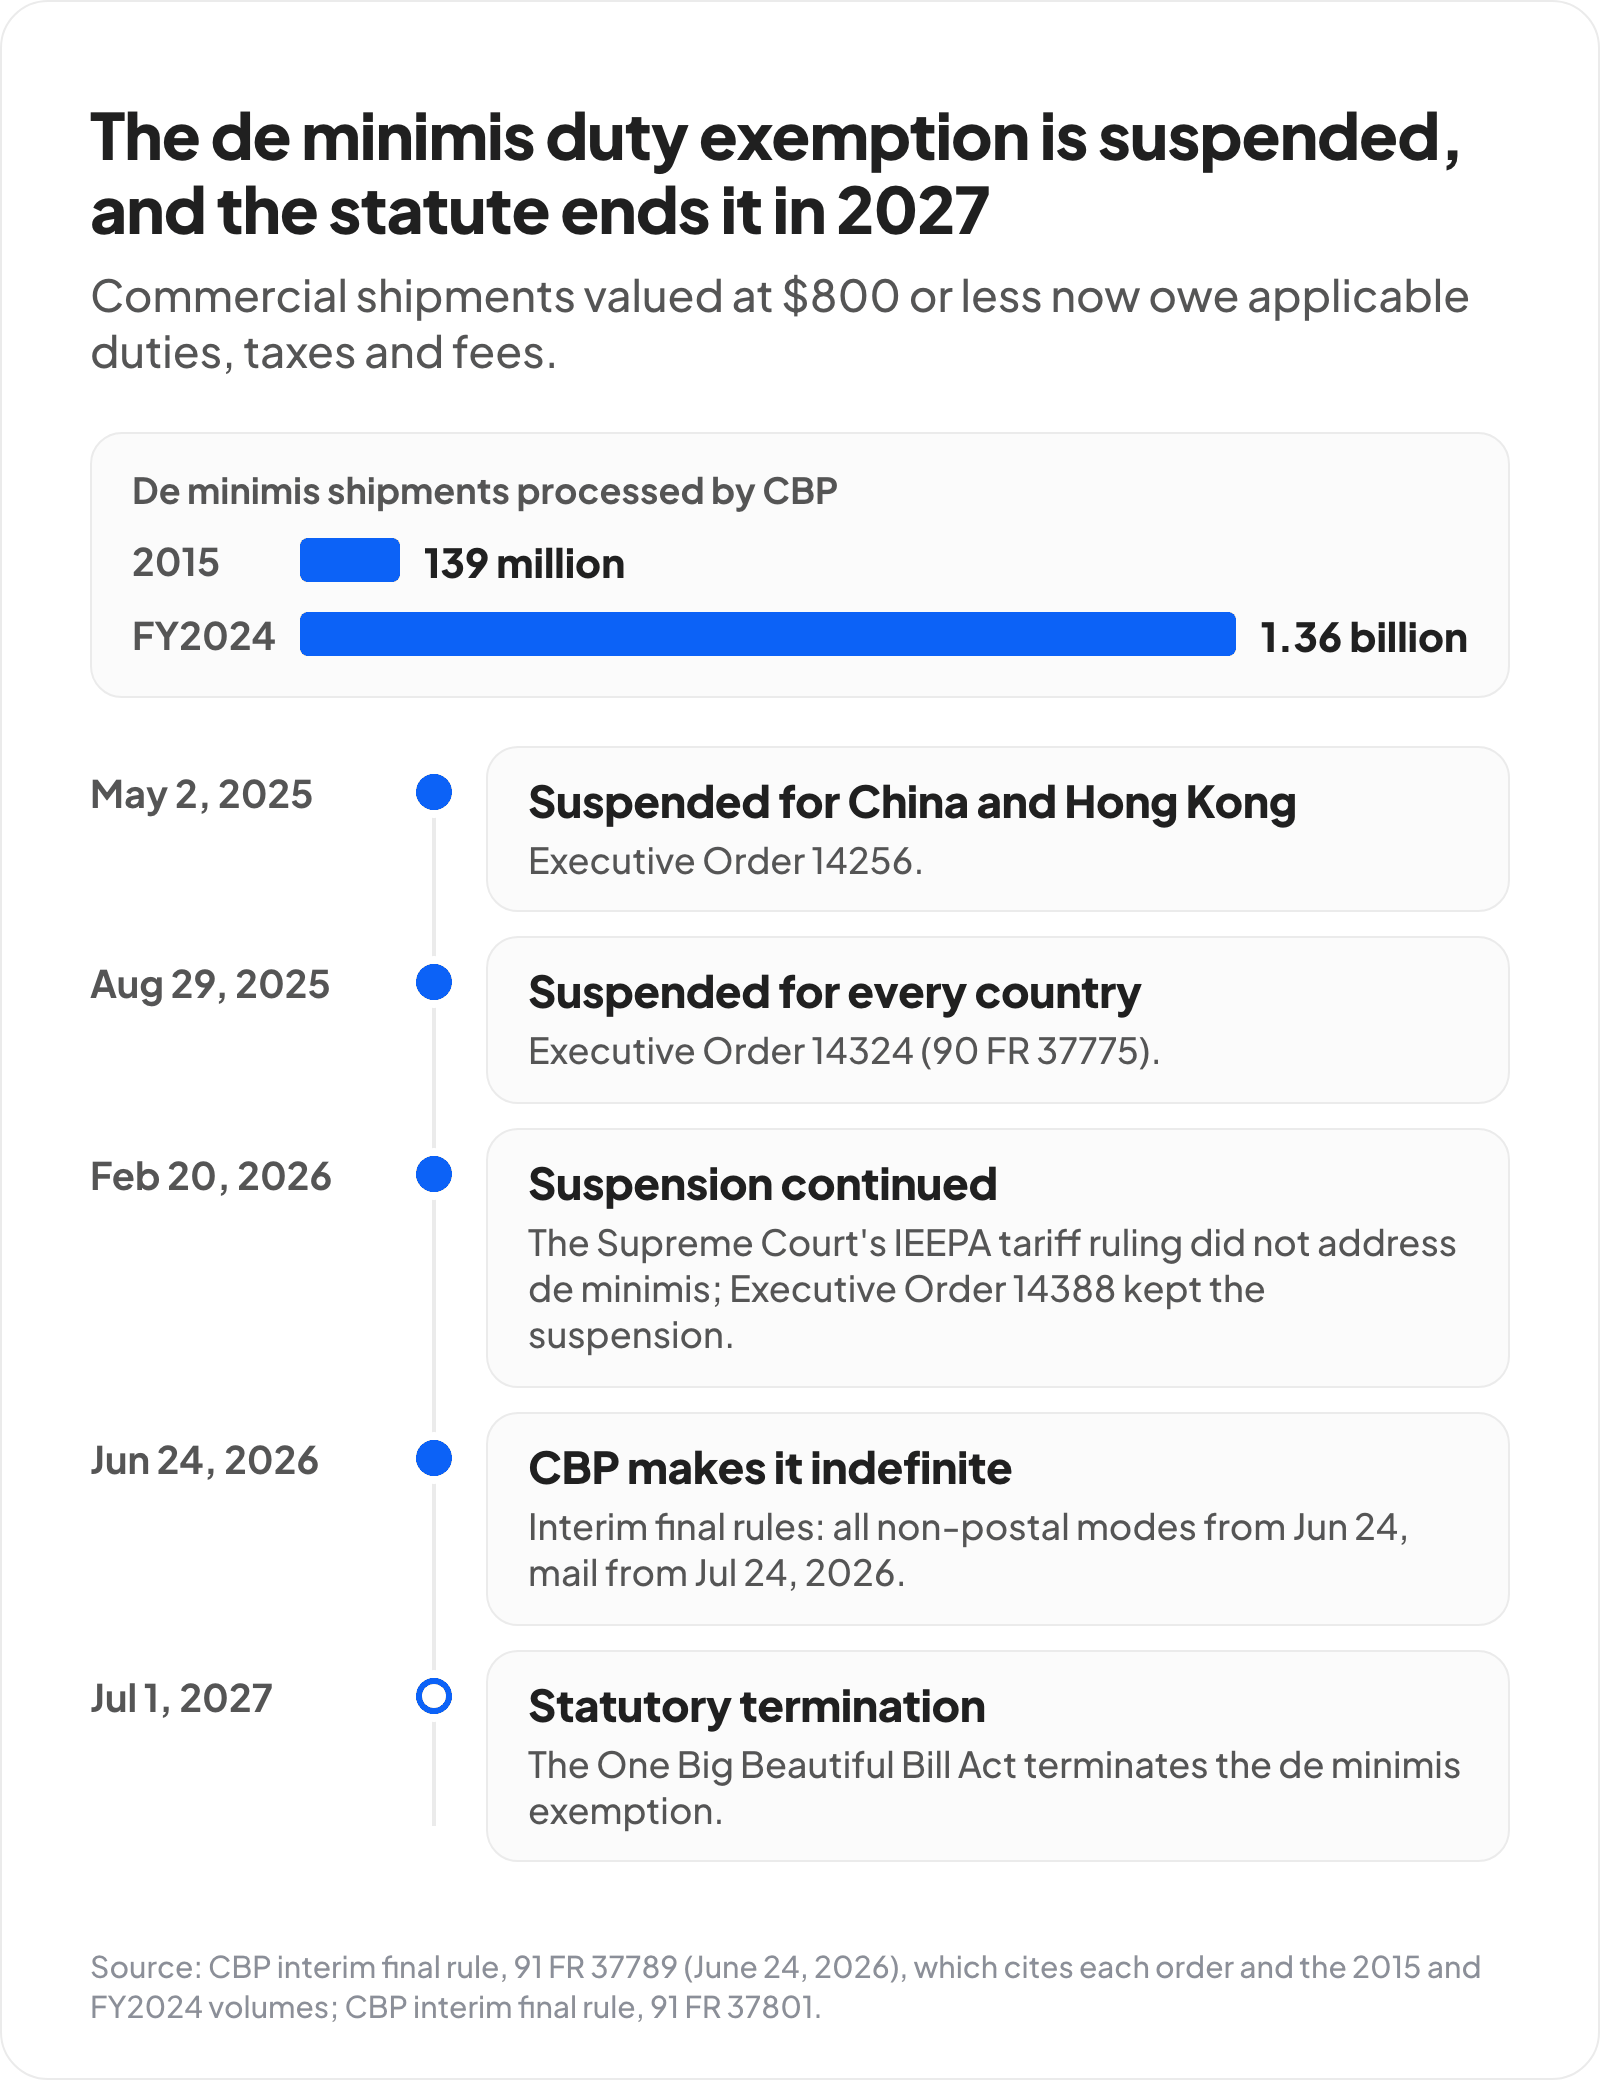
Section 321 of the Tariff Act let a shipment valued at $800 or less, imported by one person on one day, enter without duty. Volume exploded: CBP processed 139 million de minimis shipments in 2015 and more than 1.36 billion in fiscal 2024. In its June 2026 rule, CBP says many of these shipments were likely undervalued or should not have qualified, and that goods entered through its Type 86 test were often undervalued or misclassified.
The exemption is now suspended for commercial goods. It was suspended for China and Hong Kong on May 2, 2025 and for every country on August 29, 2025. The Supreme Court's February 20, 2026 ruling that IEEPA does not authorize tariffs did not address de minimis, and Executive Order 14388 continued the suspension the same day. CBP then made the suspension indefinite by interim final rules effective June 24, 2026 (non-postal shipments) and July 24, 2026 (mail). Separately, the One Big Beautiful Bill Act terminates the de minimis exemption by statute on July 1, 2027. That is also the short answer to "why am I being asked to pay import duty?" on a small parcel: commercial shipments of $800 or less now owe applicable duties, taxes and fees. Our Section 321 guide covers what replaced it.
Source: CBP interim final rules, 91 FR 37789 and 91 FR 37801 (June 24, 2026).
The bona fide gift and traveler exemptions still exist, so the risk today is a commercial parcel described as something it is not, or an older playbook that still assumes the $800 exemption applies.
What Are the Penalties for Customs Fraud?
The answer depends on which of three tracks a case takes. They can run in parallel.
CBP administrative penalties (19 U.S.C. 1592)
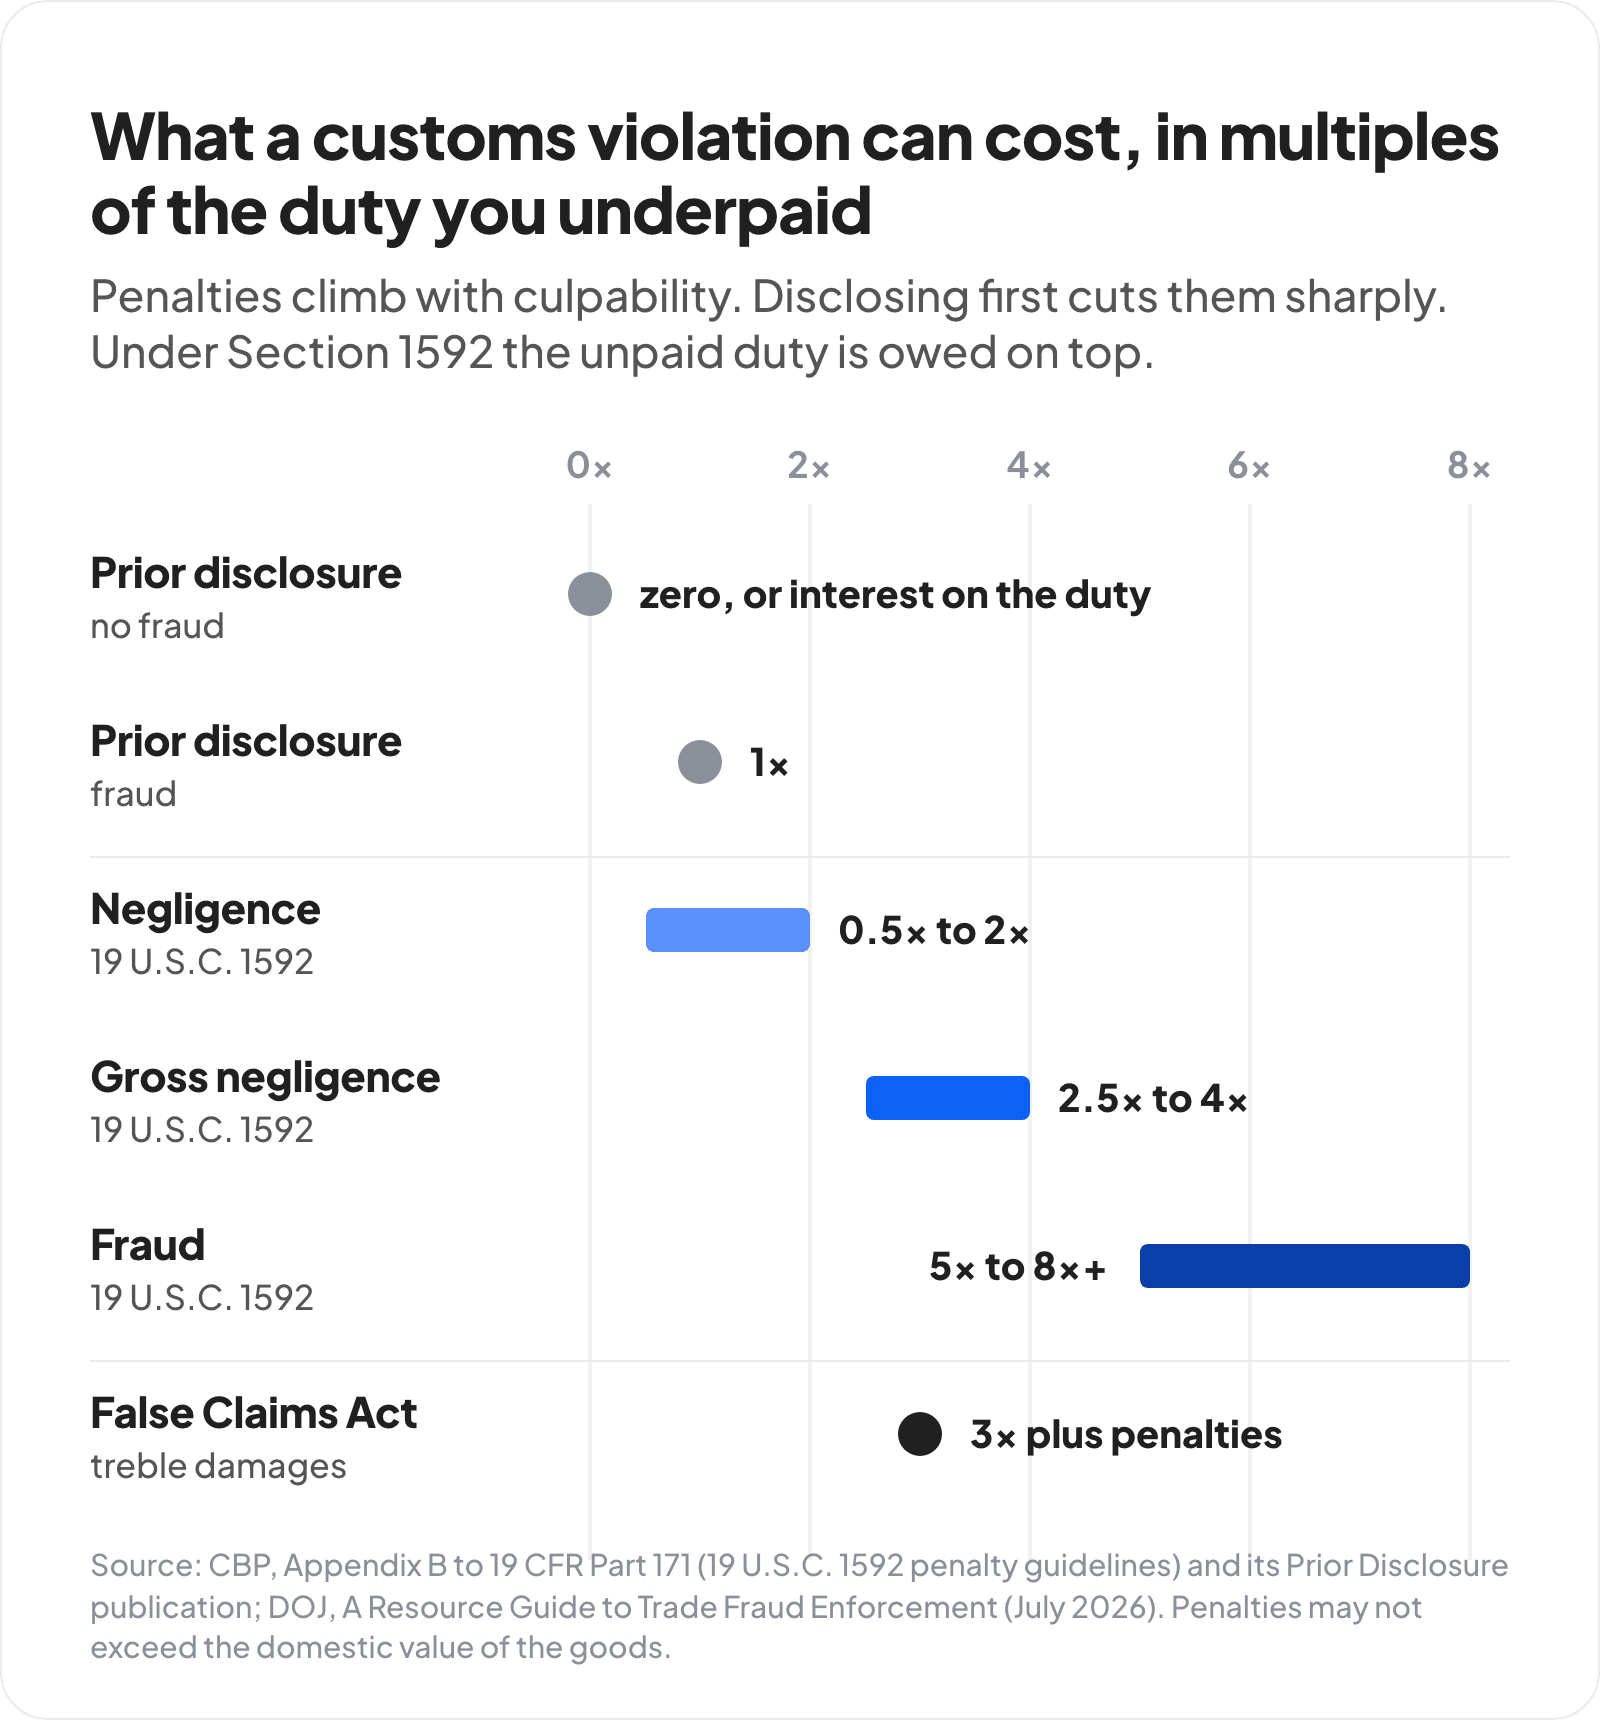
Section 1592 bars entering goods by means of a material false statement, act or omission. CBP recovers the unpaid duty and adds a penalty scaled to culpability. Under CBP's published guidelines (Appendix B to 19 CFR Part 171), penalty dispositions for a duty-loss violation run 0.5 to 2 times the lost duty for negligence, 2.5 to 4 times for gross negligence and 5 to 8 times for fraud, and never more than the domestic value of the goods. For fraud, CBP's opening claim is ordinarily the full domestic value of the merchandise.
Source: CBP penalty guidelines (Appendix B to 19 CFR Part 171) and Prior Disclosure publication; DOJ, A Resource Guide to Trade Fraud Enforcement (July 2026).
The False Claims Act
Customs cases under the False Claims Act are usually "reverse false claims": knowingly avoiding money owed to the government. The Act imposes treble damages plus penalties, reaches anyone who knowingly causes a violation, and treats deliberate ignorance and reckless disregard as "knowing". Private whistleblowers can file these suits under seal and share in the recovery, which is how the Ceratizit case started.
Criminal charges
Title 18 makes it a crime to enter goods by false classification or a fraudulent invoice (Sections 541 and 542, up to two years each). Section 545, smuggling, carries up to 20 years and forfeiture of the goods. Section 548 covers fraudulently concealing, removing or repacking merchandise in a bonded warehouse.
Prior disclosure: the way to cut the bill
If you find an error before CBP opens an investigation, a prior disclosure under Section 1592(c)(4) changes the math. CBP's publication says a non-fraud disclosure costs nothing beyond the duty on open entries, or interest on the duty for liquidated ones, and a disclosed fraud is reduced from the domestic value of the goods to 100% of the lost duty. On the criminal side, DOJ declined to prosecute plastic resin distributor MGI International in December 2025 after it voluntarily self-disclosed a scheme to falsify country of origin declarations to avoid Section 301 duties, cooperated, remediated and paid $6.8 million to resolve its civil liability under the False Claims Act. Its former chief operating officer was charged separately and agreed to plead guilty to conspiracy to smuggle goods.
Who Investigates Customs Fraud in the U.S.?
CBP reviews entries, audits importers, issues Section 1592 penalties and runs Enforce and Protect Act (EAPA) investigations into antidumping and countervailing duty evasion. In 2026, CBP said EAPA cases had uncovered more than $1 billion in additional duties owed.
The Justice Department brings False Claims Act suits and prosecutions. Its Trade Fraud Task Force, launched with DHS on August 29, 2025, reported in July 2026 that it had passed $1 billion in recoveries, penalties, forfeitures and publicly charged losses.
Anyone can report a suspected violation to CBP through its e-Allegations program, and whistleblowers can file qui tam suits under the False Claims Act.
What Tariff Fraud Means for 3PLs and Logistics Providers
A 3PL is rarely the importer of record, but enforcement no longer stops at the importer. DOJ says the Trade Fraud Task Force's mandate covers "the entire supply chain", including customs brokers, downstream distributors and "other supply-chain actors who knowingly profit from merchandise imported contrary to law." Its guide puts it more plainly: "The era when a company can claim ignorance of its upstream partners' activities is over." The Perfectus settlement named four affiliated warehousing companies alongside the importer.
For a warehouse, the practical exposure sits in the value-added services you already sell. Red flags worth a written escalation path:
a request to remove, cover or replace country of origin labels during kitting or relabeling;
inbound cartons whose markings, product or quantity do not match the commercial invoice or ASN;
two different invoices for the same shipment, or values that look far below market;
goods that arrive "made in" a country with no plausible production, or via an unusual routing;
an importer of record that looks like a shell, with no real assets or history (the DOJ guide flags shell IORs as a typology of their own).
None of this makes a 3PL a customs broker. It does mean your SOPs should say who decides when a client's paperwork does not match the freight, and that the answer is never to relabel it to match.
How Importers Can Reduce Customs Fraud Risk
Document your classifications. Keep the reasoning for every HTS code, and recheck when products or rates change.
Prove origin. Hold production evidence for any origin claim, especially where the answer changes a Section 301 or antidumping rate.
Reconcile value to payment. The declared value should match what you actually paid, including any extra charges billed on a second invoice.
Audit your broker's entries. The liability is yours even when the broker filed.
Budget duty on small parcels. Any model that relied on the $800 exemption needs repricing, and legal options such as bonded storage or a foreign trade zone deserve a look; see our guide to reducing tariffs with a 3PL strategy.
Disclose early. If you find a problem, talk to trade counsel about a prior disclosure before CBP finds it.
Find a 3PL That Handles Imported Inventory Carefully
When you choose a fulfillment partner for imported goods, ask how they handle origin labels during relabeling, inbound document mismatches and client instructions they will not follow. Fulfill.com matches brands with 3PLs based on their products and needs. Tell us what you ship and get matched with 3PLs that fit.
Get 3PL Insights in Your Inbox
Insights on choosing a 3PL, evaluating fulfillment partners, and scaling your eCommerce operation, from the team behind Fulfill.com.
What is the IMMEX program? It lets Mexican plants import inputs duty-deferred for export. Requirements, approval steps, VAT/IEPS certification and Annex 24.
FTZ vs bonded warehouse: how a foreign trade zone warehouse differs on duty rates, time limits, manufacturing and exports, with the CBP rules side by side.